There are some things in this life that we definitely need insurance for, such as for cars, homes, boats, and caravans. When it comes to being a lawn mowing contractor, do we actually need insurance to cover accidental property damage or personal injury for the work that we do? This is something every new and existing lawn mowing contractor must decide for themselves. I would never advise anyone not to have insurance, no matter what it was in respect to, and I won’t advise anything here either. Instead I will give some food for thought around the matter.
Insurance For Personal Injury
Lawn mowing insurance will cover the contractor for any personal injury done to another person while they are working. This is something very important for each of us to evaluate as to whether we would want to risk not having this insurance at all. The contractor who considers not having insurance for personal injury would need to consider their possibility of risk in this regard very carefully.
Insurance For Property Damage
The insurance we would take out would cover any accidental damage done by us as we carry out our work as lawn mowing contractors. This could include damaging a car driving past, a car sitting unoccupied near where we’re working, damaging windows or other things at a customer’s property, etc.
Insurance Excess
Like all other insurance there is an excess to pay if we claim on insurance. This means that for all property damage we might cause under a certain dollar value, we couldn’t claim anything on insurance at all because the excess we pay would cost more than the actual repair.
The excess factor means that our insurance is only useable if we damage property of high value. Otherwise we’re paying for the damage out of our own pocket anyway.
How Much Property Damage Might We Actually Cause
When considering insurance we want to consider what types of accidental property damage we might possibly cause when lawn mowing. Would these damages be of small and low value things, such as a window or a garden pot, or would we possibly be looking at damage of much higher value? What types of high value items might we possibly damage when mowing lawns?
Is Insurance Worthwhile To You
Different people will make different choices about whether to have insurance based on the following factors alone
personal injury: are we willing to risk the financial fallout of accidentally injuring a person
excess: which determines that all low value property damages are not covered by insurance at all
risk of high value property damage: what types of high value property might we possibly accidentally damage when mowing lawns which we would need insurance for
Do We Want To Do Commercial Work
If we want to do any type of commercial work of mowing lawns and gardening in Australia today, then we will quickly discover that we must have insurance for these types of work.
Businesses such as real estate agents, stratas, at home care providers, NDIS providers, schools, governments, retirement villages, and many other types of businesses will ask to see copies of our current insurance before they will hire us for anything at all.
Not all of the business types mentioned do this, but many do these days. Some might even keep records of when your insurance policy expires, and ask for records of the renewal when it’s due.
If you as a lawn mowing contractor plan to take on commercial work from the types of businesses listed, then expect to be asked regularly for your insurance documents.
Other Types Of Records Wanted By Commercial Enterprises
Some of these business types might even ask for copies of your personal medical records too. We each need to personally decide if that’s a moral line we’re willing to cross, to sacrifice our personal privacy, in order to have these types of customers in our lawn mowing rounds.
Some commercial enterprises may also ask to see police clearance records too. Retirement villages might do this, as well as schools.
Schools will probably ask for ‘working with children’ checks.
Lawn Mowing Contractors Associations
If we want to join a lawn mowing contractors association, then we may find also that some of these organisations might ask to have permanent records of our valid active insurance as a requirement for membership.
These organisations can have different reasons for doing this. One reason is to build public trust in their own brand. So that the public can go through them to find a lawn mowing contractor, and the organisation shows various aspects of the value of their own contractors. A selling point to the public here is to publicly state that all of their members carry comprehensive insurance for personal injury and property damage.
Some lawn mowing contractors associations can have relationships with insurance companies. This can be when an insurance company advertises their insurance in the newsletter of the organisation or on their website. I have no idea whether other arrangements might be in place between these parties.
Summary
Whether or not you personally decide to take out insurance for personal injury and property damage for your lawn mowing business is your choice alone. You alone must weigh up the pros and cons of this decision, and then live with that decision, no matter what happens.
There are also other aspects involved in our decision whether to take out insurance, such as if we want to take on commercial work of any kind, or if we want to join a lawn mowing contractors association.
The choice is yours.
My Take On Insurance
I won’t tell you whether I take out insurance or not. I wouldn’t want a newcomer to the industry to look at me as an example and then follow my example, which might then lead to realising they’ve made errors, no matter what they decide to do.
I will say these things.
I don’t do any commercial work of any kind. I stopped doing commercial work a long time ago, long before anyone ever started asking to see insurance papers. I don’t like these types of customers in my round, and this is for my own personal reasons.
I have never joined a lawn mowing contractors association. Though I often look back in time and wonder whether not doing so right when I started might have been a grave mistake. That team of collective knowledge must have definite advantages, especially to the newcomers, and I made a lot of mistakes. My pricing errors alone when I started would have covered the costs of membership, and given me thousands of dollars of extra income each year, if only I had some mates to teach me what’s what early on.
Potential commercial customers who have contacted me have asked to see my medical records. I told them to get lost. This is a line I would never cross.
In a quarter century of lawn mowing I have
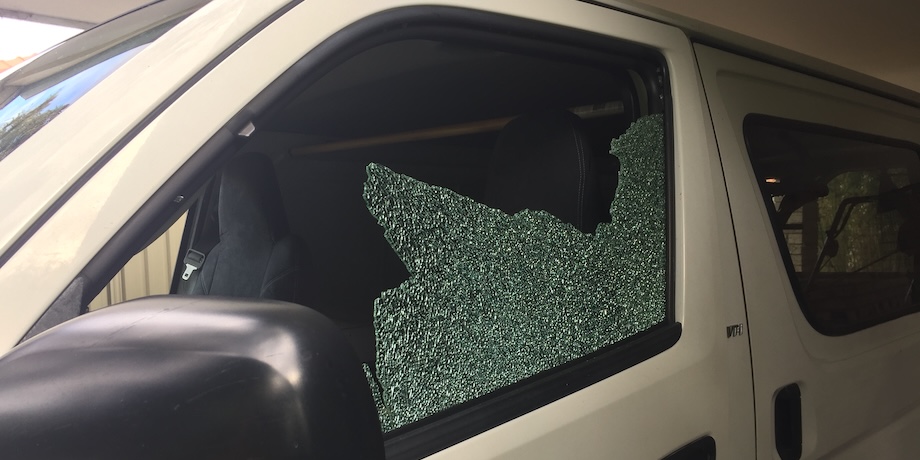
broken glass on my own vehicle 3 times
broken a window at customers houses twice
broken a large clay garden pot
I have broken a water meter
even stepped on and broke a garden gnome once
The cost of these breakages has averaged to $40.00 per year.
I have never claimed any damages on insurance a single time, except for when I broke glass on my own vehicle, which my vehicle insurance covered.
I learned from my errors in earlier years, and I changed aspects of my lawn mowing practices. These changes should have greatly reduced the risk of ever breaking glass or a water meter at a customer’s property ever again.
I have never injured myself to any degree past the usual nuisance cuts and bruises and bumping into a low hanging tree branch.
I have never caused injury to any other person, not even a scratch.
all articles and images are © copyright
thelawnmowingman.com